View Charts
Market Reaction to PPI Report and Mixed Bank Earnings
 0
U.S. Equity Futures Response
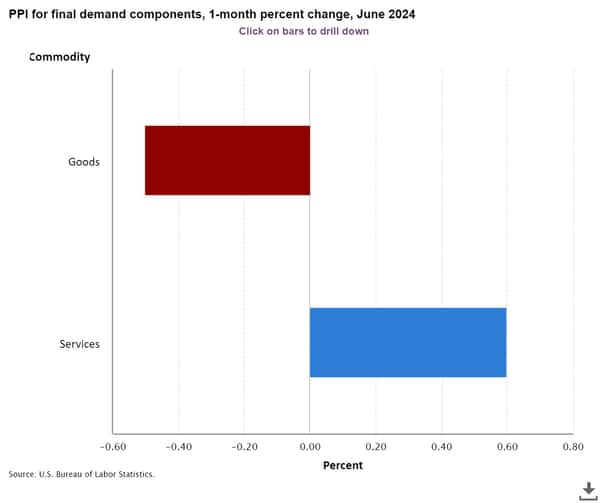
U.S. equity futures are showing little change, erasing earlier gains as the market continues yesterday's rotation. As of 8:45 AM, S&P futures are flat after the index dropped nearly 1% in the previous session. The 10-year Treasury yield remains unchanged at 4.21%, and the USD is slightly lower despite a hotter-than-expected Producer Price Index (PPI) report. Commodities are mixed, with oil prices rising while base metals decline. The primary market focus today includes the PPI report, which showed stronger-than-expected results, and mixed earnings reports from major banks.
Bank Earnings Highlights
In premarket trading, several notable movements include:
- Wells Fargo: Dropped 5% after warning it won't be able to reduce costs as quickly as forecast due to higher-than-expected expenses.
- JPMorgan: Fluctuated between gains and losses despite reporting record profits but missing key metrics like net interest income.
- Citigroup: Climbed 3% as equity trading beat estimates, though the lender mentioned higher-than-expected annual costs.
Additional Premarket Movers
- Tesla: Fell 1% after UBS downgraded its rating to sell, citing the stock’s rapid rally.
- Array Technologies: Rose 5% following a Citi upgrade to buy, highlighting growth potential.
- AT&T: Slipped 2% amid news of a significant data hack affecting call and text records from 2022.
- Bally’s: Increased 1% after securing a funding commitment from Gaming and Leisure Properties.
- JPMorgan: Dropped 1% despite positive investment banking revenue, with CEO Jamie Dimon noting persistent inflation and rate concerns.
Economic Indicators
U.S. producer prices increased more than forecast in June, driven by higher margins at service providers, which offset declining goods costs. Investors eagerly anticipate insights from major banks regarding the U.S. economy and the potential impacts of the forthcoming presidential election.
European Market Performance
In Europe, the Stoxx 600 rose 0.2%, marking its third consecutive day of gains, led by energy and consumer product shares. Notable movers include:
- Ericsson: Surged up to 9.3% following stronger-than-expected sales.
- Addtech: Increased by as much as 13% due to a solid Q1 report.
- Lifco: Jumped 12% after exceeding quarterly net sales expectations.
- Norwegian Air: Rose 8.2% following a better-than-expected EBIT in Q2.
Asian Market Performance
Asian stocks saw declines, particularly in tech shares, tracking losses in the U.S. due to slowing inflation data. However, Hong Kong's market bucked the trend with gains amid hopes for lower borrowing costs. Significant movements include:
- BOC Aviation: Rose 5.3% after closing a major loan transaction.
- CK Infrastructure: Spiked by 7.5% following the consideration of a potential second listing on an overseas stock exchange.
- BayCurrent: Increased 19% following strong Q1 results.
- Chalco: Jumped 10% after a JPMorgan upgrade.
- Seven & I: Plummeted 8.4% following disappointing Q1 earnings.
FX and Commodity Markets
The yen experienced fluctuations against the dollar due to speculation about potential Japanese intervention. The Bloomberg Dollar Spot Index fell 0.1%, and the Swedish krona weakened against the greenback after slower-than-expected inflation data. Treasuries edged lower, with U.S. 10-year yields rising slightly. In commodities, oil prices advanced, with WTI nearing $83.50 per barrel, while gold prices fell to around $2,404 per ounce.
Conclusion
Today's market landscape reflects a complex interplay of economic data, earnings reports, and geopolitical factors. Investors are closely monitoring inflation indicators and central bank responses, which will shape market trends in the coming months. The mixed performance across different sectors and regions underscores the cautious optimism prevailing in the market.
Market Snapshot
- S&P 500 Futures: Little changed at 5,643.50
- STOXX Europe 600: Up 0.3% to 521.21
- MXAP: Down 0.6% to 187.44
- Nikkei: Down 2.4% to 41,190.68
- Hang Seng Index: Up 2.6% to 18,293.38
- German 10Y Yield: Rose 4bps at 2.51%
- Euro: Up 0.1% to $1.0884
- Brent Futures: Up 0.9% to $86.16/bbl
- Gold Spot: Down 0.4% to $2,406.32
Top Overnight News
- Biden's NATO Remarks: Mistakenly referred to Ukrainian President Zelensky as President Putin and VP Harris as Trump.
- SoftBank Acquisition: Acquired U.K. semiconductor company Graphcore.
- Fed's Goolsbee: Praised the June CPI report, signaling a steady policy rate.
- China Trade Data: Record monthly trade surplus driven by export surge.
Key Focus
- Economic Data: June PPI and preliminary University of Michigan sentiment.
- Earnings Reports: BNY Mellon, Wells Fargo, Citigroup and JPMorgan.
This comprehensive overview highlights the current market dynamics and the key factors influencing investor sentiment and market performance.