View Charts
Bank Outages, Grounded Flights & Cyberattacks: Why Physical Gold Matters
 0
A Week of Disruptions Exposes a Different Kind of Financial Risk
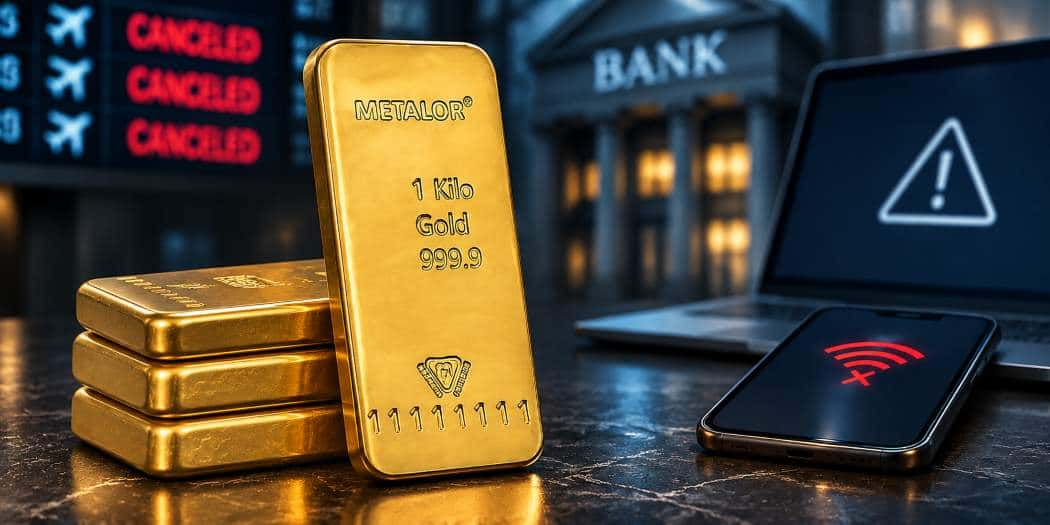
On November 16, customers of JPMorgan Chase encountered transaction delays caused by a software malfunction. That same afternoon, United Airlines experienced a separate technology outage affecting departing flights. Three days earlier, a telecommunications failure had forced the Federal Aviation Administration to suspend departures nationwide. Across Europe, suspected cyberattacks had recently disrupted supermarket refrigeration systems, forcing retailers to discard spoiled food.
These incidents involved different industries, causes, and consequences. None establishes that a coordinated attack or financial collapse is underway. Yet their timing raises a question that extends beyond cybersecurity: what happens when an asset retains its value, but the systems required to access or use it temporarily stop working?
For gold investors, that distinction deserves attention. Physical bullion offers a form of ownership independent of banking applications and electronic account records. Understanding where that independence matters, and where its advantages end, is increasingly relevant in an economy built around interconnected financial infrastructure.
What the Banking and Aviation Failures Actually Revealed
The November 16 banking disruption began with a software problem affecting JPMorgan Chase's transaction processing. According to Reuters' reporting on the incident, the bank said customers retained access to their accounts and funds, although some transactions were taking longer than usual. Other institutions could experience delays when processing payments involving Chase, even without suffering independent system failures.
The distinction matters because reports of problems at multiple banks can create the impression of a broader breakdown. Chase said there was no evidence of a cyberattack and characterized the malfunction as an isolated technical issue. Zelle's network also remained operational, although individual transfers involving affected banking relationships could be delayed.
The aviation disruptions demonstrated a different form of technological dependence. On November 13, instability in the FAA's telecommunications network prompted a nationwide ground stop lasting approximately four hours and 45 minutes. The agency reported that 17 of its 22 Air Route Traffic Control Centers experienced instability and that approximately 12,462 flights were canceled that day, although not every cancellation was directly attributable to the incident.
In its official explanation of the ground stop, the FAA identified excessive network traffic involving legacy equipment and equipment changes as central investigative issues. Officials reported no indication of a cyberattack. United Airlines then experienced a separate, shorter technology disruption on November 16 that delayed departures without affecting aircraft already in flight.
The incidents exposed operational vulnerabilities, not evidence of a shared cause. Their relevance to investors lies in how quickly otherwise functioning services can become temporarily inaccessible.
European Supermarket Incidents Extend the Concern Beyond Finance
Earlier in November, supermarkets across several European countries encountered refrigeration failures associated with suspected cyberattacks. Retailers in Belgium, Sweden, Ireland, Portugal, and other countries reported problems with remotely managed cooling equipment. Some stores discarded food after refrigeration temperatures rose beyond acceptable levels.
As Euronews reported on November 3, the incidents affected retailers in nine countries. Investigations pointed toward vulnerabilities involving connected refrigeration controls and, in some cases, external technology providers. These were targeted equipment disruptions, not evidence of nationwide European electricity blackouts.
Their significance becomes clearer when considered alongside the banking and aviation incidents. A payment system, air traffic network, and supermarket refrigeration controller perform entirely different functions, but each depends on infrastructure that users rarely see. When a critical component fails, the resulting disruption can extend well beyond the original technical problem.
For individuals considering financial resilience, this creates a practical distinction between owning resources and depending on an uninterrupted network to make those resources usable.
Physical Gold Removes One Layer of Financial Dependence
Most financial assets involve some degree of institutional access. Bank deposits require functioning account systems and payment channels. Brokerage holdings depend on custodians, trading platforms, and settlement infrastructure. Even an investor with substantial assets may encounter temporary restrictions on moving or spending funds when those systems malfunction.
Directly owned physical gold operates differently. A bullion coin or bar remains in its owner's possession regardless of whether an online banking portal, brokerage application, or electronic transfer network is available. Its existence does not depend on a financial institution displaying a balance or successfully processing a transaction.
That advantage concerns custody rather than guaranteed purchasing power. Gold prices fluctuate, and direct ownership introduces responsibilities involving security, insurance, storage, and resale. Nevertheless, the distinction between holding metal and holding a financial claim linked to metal becomes especially relevant when evaluating exposure to intermediaries.
A person purchasing physical gold bars, for example, acquires a tangible asset that can be independently possessed and authenticated. That differs operationally from holding a gold exchange-traded fund, whose shares provide market exposure through the securities system.
Neither arrangement is universally superior. Electronic products can offer convenient trading and account integration, while physical bullion provides direct possession. Investors concerned about temporary infrastructure disruptions may value that difference without assuming that conventional financial institutions are inherently unsafe.
Gold Cannot Replace Cash When Payment Systems Stop Working
The appeal of physical gold during technological disruptions is easily overstated. A gold coin may remain valuable when card terminals fail, but that does not mean a grocery store will accept it as payment. Even a willing merchant would need to establish authenticity, determine a fair exchange value, and provide change for a relatively high-value asset.
Cash generally serves short-term emergency spending more effectively. It can facilitate ordinary transactions when electronic payments are unavailable, provided businesses remain operational and accept banknotes. Physical gold addresses a longer-term concern: maintaining a portion of wealth in an asset that does not require continuous digital access merely to remain owned.
The distinction also affects product selection. Smaller gold coins can provide greater flexibility when selling portions of a holding, although fractional denominations often command higher premiums relative to their metal content. Larger bars may offer lower premiums but require selling more value in a single transaction.
Those trade-offs differ from the considerations surrounding emergency barter. Our guide to gold and silver for preppers explores that broader subject. The recent outages instead highlight a narrower question: whether investors have diversified the mechanisms through which they hold and access their wealth.
Physical bullion can contribute to that diversification, but it should complement accessible savings and practical emergency resources rather than replace them.
The Real Test Is What Happens When Gold Must Be Sold
Possessing gold independently of banking infrastructure does not eliminate the need for functioning markets. Converting bullion into dollars generally requires a buyer, authentication, an agreed price, and a settlement method. During a widespread communications failure, some of those services could be temporarily unavailable.
Storage arrangements create another important distinction. Gold kept at home may be immediately accessible but introduces theft and security concerns. Metal held in professional vaults may benefit from stronger safeguards, although withdrawals depend on the provider's procedures and operating conditions. The guide to storing precious metals explains these practical differences.
Liquidity also depends on market conditions. The quoted spot price of gold provides a reference point, but actual resale proceeds reflect dealer spreads, product characteristics, and prevailing demand. A temporary banking outage does not automatically increase gold prices, and there is insufficient evidence to attribute a specific gold-market movement to the November incidents.
The lesson from this month's disruptions is therefore more precise than the suggestion that gold protects against every emergency. Digital infrastructure can temporarily restrict access to otherwise intact financial resources. Direct ownership of bullion reduces certain custody dependencies, but its usefulness still depends on security, market access, and the owner's broader financial arrangements.
As financial services become increasingly interconnected, those distinctions deserve consideration before the next disruption, not merely while one is unfolding.