View Charts
Weekly Market Report: Precious Metals & Crypto Trends — Oct. 16, 2026
 0
Hot Inflation Keeps Precious Metals and Crypto Under Pressure
Precious metals and cryptocurrencies are ending another volatile week as investors weigh stubborn U.S. inflation against shifting expectations for Federal Reserve interest rates. Gold and silver have recovered some ground from their midweek declines, but the improvement has not been enough to reverse their weekly losses. Platinum and palladium also remain below last Friday's levels, while Bitcoin and Ethereum reflect continued caution across risk-sensitive markets.
The week's defining development was a combination of unexpectedly strong inflation reports and a changing interest-rate outlook. Wednesday's September Consumer Price Index showed annual inflation reaching 3.7%, while Thursday's Producer Price Index rose 1.3% month over month. Those figures initially strengthened the dollar, lifted Treasury yields, and triggered substantial selling in gold and silver. The Federal Reserve's Beige Book also highlighted business concerns about elevated energy costs.
Friday brought a more complicated picture. Federal Reserve Chair Kevin Warsh emphasized price stability during remarks at the International Monetary Fund meetings but offered no clear signal that another rate increase would occur in October. Markets subsequently reduced expectations for an immediate hike, helping gold recover as the dollar and bond yields eased. Meanwhile, technology-stock volatility and geopolitical concerns continued to influence investor sentiment.
Precious Metals and Cryptocurrency Weekly Price Overview
The October 16 morning snapshot shows that all four major precious metals are trading below their October 9 levels. Silver has suffered the steepest percentage decline, followed by platinum, palladium, and gold. That ranking illustrates how industrial demand expectations and changing financial conditions can amplify silver's volatility relative to gold.
Cryptocurrency markets have also weakened on a Friday-to-Friday basis. Bitcoin has held up better than Ethereum, although both remain sensitive to Treasury yields, technology-sector sentiment, and expectations for monetary policy. Friday's recovery in some precious metals should therefore be viewed against a broader week of declining prices rather than as evidence of a sustained market reversal.
Market Snapshot: Prices as of 9:30 AM ET
The following prices reflect the October 16, 2026, 9:30 AM ET morning snapshot supplied for this report. Percentage changes are calculated against the October 9, 2026, 9:30 AM ET prices.
|
Asset |
October 16 price |
Change from October 9 |
|
$4,171.10/oz |
−0.67% | |
|
$57.77/oz |
−5.53% | |
|
Platinum Price Today |
$1,651.80/oz |
−2.60% |
|
Palladium Price Today |
$1,150.50/oz |
−1.75% |
|
Bitcoin Price Today |
$81,883.20 |
−1.20% |
|
Ethereum Price Today |
$2,458.55 |
−1.41% |
Gold Market Trends: Inflation Shock Tests Bullion's Resilience
Gold experienced a difficult midweek selloff after inflation data increased expectations for additional Federal Reserve tightening. Higher yields and a stronger dollar initially made non-yielding bullion less attractive, but Friday's recovery showed how quickly sentiment can change when interest-rate expectations are reassessed. Gold's relatively modest weekly decline suggests that defensive demand has helped cushion the market against more aggressive selling.
Key Drivers:
-
Hotter CPI and PPI readings intensified concerns about restrictive monetary policy.
-
Fed Chair Warsh avoided signaling an immediate October rate increase.
-
Softer Treasury yields and dollar weakness supported Friday's recovery.
-
Technology-stock volatility contributed to interest in defensive assets.
Silver Market Trends: Weekly Losses Exceed Gold's Decline
Silver has endured a substantially sharper weekly decline than gold, reflecting its greater sensitivity to both monetary conditions and expectations for industrial activity. The metal fell heavily following Wednesday's inflation surprise before recovering as yields retreated. Although its applications in electronics, solar technology, and manufacturing remain important sources of demand, this week's price action has been dominated by macroeconomic developments rather than a confirmed change in industrial supply.
Key Drivers:
-
Inflation-driven selling produced a sharper decline than in gold.
-
Changing Treasury yields increased volatility throughout the week.
-
Friday's weaker dollar helped restore some buying interest.
-
Manufacturing expectations remain relevant to silver's longer-term outlook.
Platinum Market Trends: Industrial Demand Meets Monetary Uncertainty
Platinum remains below last Friday's morning level despite participating in the broader recovery across precious metals. Its market faces competing influences: easing financial conditions can encourage investment interest, while elevated borrowing costs and uncertainty about manufacturing activity can weigh on industrial demand. Automotive catalysts remain an important source of consumption, alongside chemical processing and other industrial applications. No newly verified supply disruption explains this week's decline.
Key Drivers:
-
Restrictive interest-rate expectations pressured industrial precious metals.
-
Automotive production remains important to platinum consumption.
-
Concentrated mine supply continues to create structural exposure.
-
Dollar weakness provided some support toward the end of the week.
Palladium Market Trends: Automotive Uncertainty Persists
Palladium has declined over the week, although its losses have been less severe than those recorded by silver and platinum. Unlike gold, palladium depends heavily on demand for catalytic converters in gasoline-powered vehicles. That exposure leaves it vulnerable to changes in automotive production, electrification, and manufacturers' decisions about platinum substitution. Supply concentration in Russia and South Africa remains important, but no specific new production or inventory event has been established as the principal driver of this week's performance.
Key Drivers:
-
Automotive demand expectations continue to influence palladium.
-
Platinum substitution remains a longer-term market consideration.
-
Inflation and interest-rate uncertainty affected industrial metals.
-
Russian and South African supply concentration remains a structural risk.
Crypto Market Trends: Bitcoin and Ethereum Face Risk-Off Trading
Bitcoin and Ethereum are finishing the week lower as cryptocurrency investors navigate shifting interest-rate expectations and weakness in technology-related equities. Bitcoin briefly traded below the psychologically important $80,000 level during the week's volatility before recovering, while Ethereum also struggled to regain momentum. The Federal Reserve's uncertain policy path remains important because changes in liquidity and borrowing costs can influence demand for speculative assets.
Key Drivers:
-
Higher inflation increased concerns about additional Fed tightening.
-
Technology-stock volatility weakened broader risk appetite.
-
Shifting Treasury yields contributed to cryptocurrency price swings.
-
An October 13 CFTC regulatory proposal introduced a separate policy development for crypto markets.
What to Watch Next Week: Housing Data, Consumer Sentiment, and Fed Policy
The week of October 19–23 will provide a different set of economic signals after the inflation-heavy calendar that dominated this week's trading. With the Federal Reserve's October 27–28 meeting approaching, investors will focus on whether incoming activity data supports another rate increase or gives policymakers room to pause.
Housing indicators and consumer sentiment will be particularly relevant. A slowing economy could reduce pressure for tighter monetary policy, potentially supporting gold and silver. Conversely, resilient activity combined with persistent inflation could keep Treasury yields elevated and limit recoveries across precious metals and cryptocurrencies.
Several scheduled developments deserve attention:
-
October 20 — Housing Starts and Building Permits: September residential construction figures will offer insight into how elevated financing costs are affecting housing activity.
-
October 20 — Pending Home Sales: The National Association of Realtors' pending sales report will provide another indication of housing-market demand.
-
October 22 — Weekly Jobless Claims: Labor-market data could influence expectations for economic resilience and the Fed's next policy decision.
-
October 23 — Final October Consumer Sentiment: The University of Michigan's revised survey will provide further evidence about household confidence and inflation expectations.
-
October 23 — New York Fed Nowcast: Updated growth estimates may help investors assess whether the economy is slowing sufficiently to influence monetary policy.
-
October 27–28 — Upcoming FOMC Meeting: Although scheduled for the following week, the meeting will remain central to trading decisions as investors evaluate the likelihood of another rate increase.
-
Energy Markets and Geopolitical Risk: Developments involving Middle East shipping, Russian energy infrastructure, and oil prices could alter inflation expectations.
-
Dollar and Treasury Yield Movements: Another increase in either could renew pressure on gold, silver, and cryptocurrencies.
The central question is whether economic growth remains strong enough to justify tighter policy despite signs of strain in some financial markets. For precious metals, the direction of real yields and the dollar may prove more influential than any individual data release.
A Precious Moment of Levity: Even the Markets Could Use a Festival of Lights
After a week of inflation surprises, shifting Fed expectations, and unpredictable price swings, investors might appreciate a little more light and a little less market drama. With Diwali celebrations approaching, the festival's themes of light, prosperity, and new beginnings offer a timely contrast to the week's unsettled trading. Bullion Exchanges' gold and silver Diwali deals bring that seasonal connection into the precious-metals market. Whether next week delivers a brighter outlook or another round of volatility, investors will be watching the dollar, Treasury yields, and Federal Reserve expectations for signs of where prices may head next.
Check out Today’s Daily Deal!
At Bullion Exchanges, we’re committed to offering you unbeatable prices on premium precious metals every day. Whether you’re investing, collecting, or gifting, our deals are designed to help you maximize value while building your portfolio.
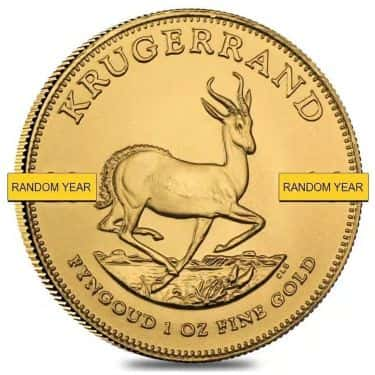
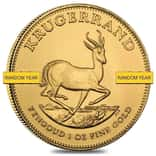
Own a piece of gold bullion history with the 1 oz South African Krugerrand Gold Coin BU (Random Year)! First introduced in 1967, the Krugerrand became the world's first modern gold bullion coin and remains a favorite among investors and collectors. Each coin contains 1 troy ounce of actual gold in a durable .9167 fine gold alloy, featuring the iconic Springbok antelope and Paul Kruger designs. With its worldwide recognition, timeless appeal, and rich heritage, the Krugerrand is a classic addition to any precious metals collection. Random-year coins are selected from available inventory.